How to Consolidate High‑Interest Debt with a Personal Loan in India
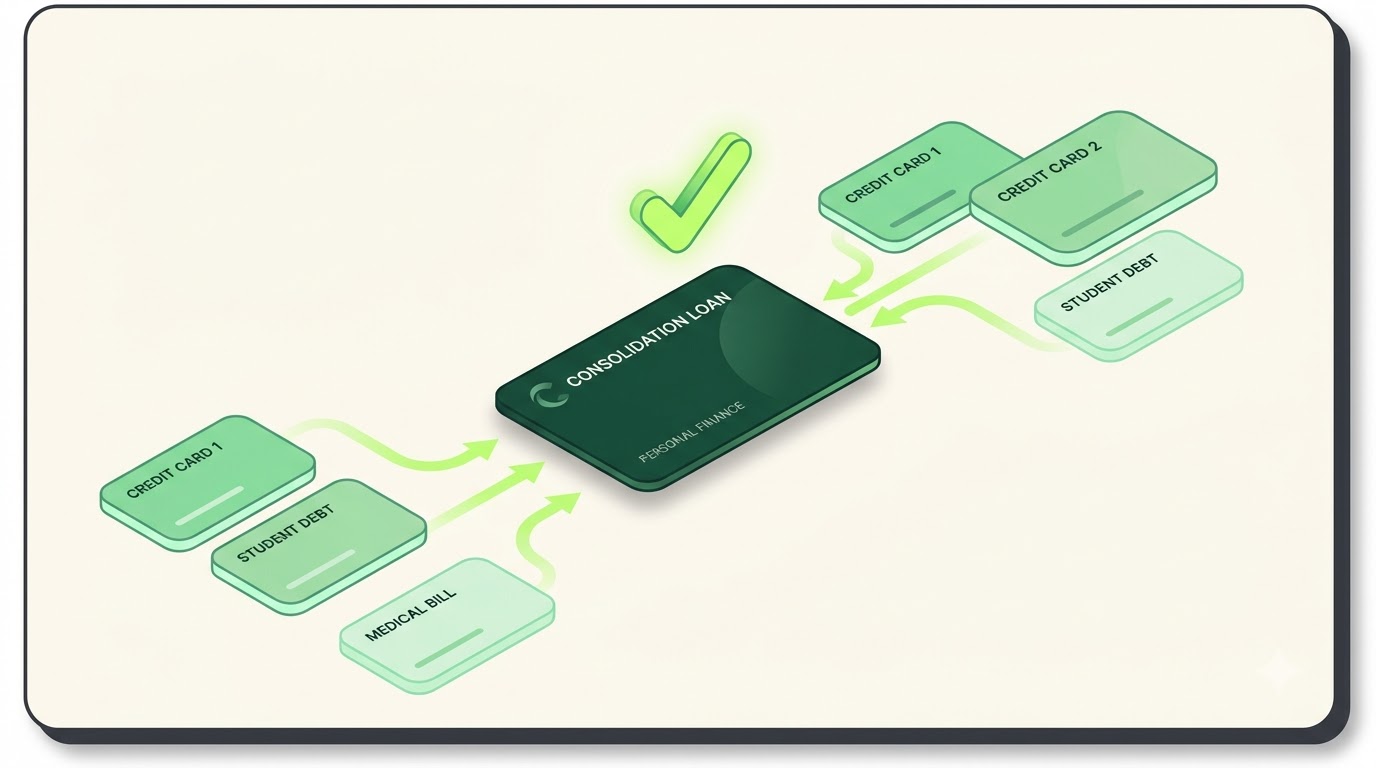
Many borrowers struggle to manage several loan EMIs with different due dates and interest rates. A personal loan used for debt consolidation can combine those obligations into one manageable payment, simplifying repayment and often lowering the total interest cost.
How a Personal Loan Can Consolidate Your Debt
A personal loan taken for debt consolidation provides a lump sum that you use to pay off all existing high‑interest debts. After the existing balances are cleared, you repay the loan through a single fixed EMI each month for the agreed repayment period.
How the Consolidation Process Works
First, you apply for a personal loan that covers the total amount you owe across all current debts. Once the loan is approved and the funds are transferred to your bank account, you use the money to settle each outstanding balance. After those debts are closed, you begin making one EMI payment each month until the loan is fully repaid.
Eligibility and Application Process
Typical eligibility includes being of legal age, having a stable source of income, and maintaining a satisfactory credit profile. The application can be completed online with minimal documentation; after verification, the lender disburses the amount directly to your account, allowing you to clear the existing loans promptly.
Common Mistakes to Avoid
Borrowing an amount higher than the total of your current debts can lead to unnecessary interest costs. Choosing a longer repayment period solely to lower the EMI may increase the total amount paid. Ignoring processing fees or pre‑payment penalties can also reduce the benefit of consolidation. Review the loan terms carefully and ensure the new EMI fits comfortably within your budget.
Choosing the Right Consolidation Option
Compare offers from different lenders focusing on the interest rate range, any associated fees, the flexibility of the repayment schedule, and the quality of customer support. A lower rate can save money over time, while a flexible tenure helps you match the EMI to your cash flow. Using online calculators and reading reviews can give a clearer picture of the total cost.
How Credit91 Can Help
Credit91 operates as a lending service provider that partners with RBI‑regulated NBFCs. It can assist you in reviewing eligible personal loan offers, simplifying the application steps, and connecting you with the appropriate lender for debt consolidation.
Final Thoughts
Consolidating multiple high‑interest debts into a single personal loan can improve cash flow, reduce the number of payments you need to monitor, and potentially lower the total interest you pay. Taking the first step by checking your eligibility and exploring suitable loan options can set you on a path toward financial stability.
Disclaimer
This article is for educational purposes only. Loan eligibility, terms, charges, and approval depend on the applicable lender's policies and the applicant's profile. Readers should verify the latest information before making financial decisions.
Frequently Asked Questions
Can a personal loan be used to pay off credit card balances?
Yes, a personal loan can be used to clear credit card balances, often at a lower interest rate than the cards, which helps reduce overall debt cost.
What documents are typically required for a personal loan application?
Common documents include proof of identity, proof of address, income proof such as salary slips or bank statements, and sometimes proof of employment. The exact list may vary by lender.
Will consolidating my debts affect my credit score?
Making timely payments on the consolidated loan can improve your credit score over time, while missed payments can have a negative impact. The overall effect depends on how you manage the new loan.
Is there any penalty for paying off the consolidated loan early?
Many lenders allow pre‑payment after a certain period without penalty, but you should check the specific terms of your loan agreement to confirm.